PIX Payment Integration for Online Casinos in Brazil: The Operator's Complete iGaming Payment Solution Guide for 2026
Why Is PIX the Non-Negotiable iGaming Payment Solution for Brazil in 2026?
PIX is the Banco Central do Brasil's instant payment infrastructure, launched in November 2020. By 2024 it had surpassed credit cards as the most-used payment method in Brazil, with over 60 million daily transactions. For casino operators, PIX means instant deposits, sub-minute withdrawals, and near-zero chargebacks, a combination no other Brazilian payment method comes close to matching.
Brazil's iGaming market opened for licensed operation under Lei 14.790/2023, and the regulatory framework that followed explicitly tied licensed operators to compliant payment channels. That means PIX is not just a user preference, it is functionally the only scalable, compliant deposit and withdrawal method for a regulated Brazilian casino. Boleto bancário still exists but settles in one to three business days, which is a conversion killer. Credit cards face high issuer decline rates for gambling MCC codes. PIX has none of those problems.
The numbers are stark. In operator data I have reviewed from Brazilian-facing platforms (not named for NDA reasons), PIX accounts for 85 to 95 percent of all deposits on mobile-first casino products. The average deposit ticket sits between BRL 50 and BRL 200, and users expect to see their balance credited within seconds of completing the QR code scan. Any latency above 30 seconds triggers support tickets. Any withdrawal that takes more than 15 minutes starts generating churn. These are not hypotheticals, they are the benchmarks your PSP contract needs to be written around.
There is also a fraud profile advantage. PIX transactions are tied to a CPF (individual taxpayer ID) or CNPJ, which means every transaction carries identity metadata baked in at the infrastructure level. That does not eliminate fraud, but it dramatically simplifies AML transaction monitoring and player verification workflows compared to card-based flows where BIN data is your primary signal. For operators building a compliance stack under SECAP/MF rules, that identity linkage is genuinely useful.
How Does PIX Actually Work at the Technical Level for Casino Integrations?
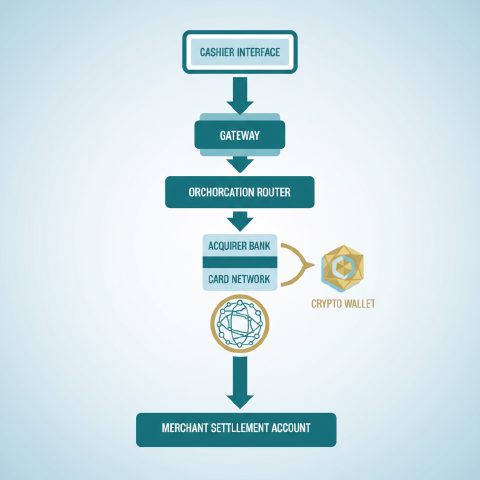
PIX operates through the SPI (Sistema de Pagamentos Instantâneos) managed by Banco Central do Brasil. Casinos do not connect to SPI directly. They connect via a Payment Institution (IP) or a PSP that holds a direct SPI participant license. The casino's platform calls the PSP's API to generate a PIX Copia e Cola string or QR code, the player pays, and the PSP posts a webhook to confirm settlement, typically in under 10 seconds.
The technical flow for a deposit looks like this: the player selects PIX at checkout, your platform backend calls the PSP's charge creation endpoint with the amount and a unique external reference, the PSP returns a base64-encoded QR code image and the raw PIX key string (Copia e Cola), the player scans or pastes in their banking app, and the PSP fires a POST to your webhook URL confirming the credit. Your platform then credits the player wallet and logs the transaction against their CPF. That CPF matching step is where a lot of operators cut corners and later regret it, more on that in the compliance section.
For withdrawals (saques), the flow reverses. Your platform calls the PSP's payout endpoint with the player's PIX key (CPF, phone, email, or random key), the amount, and your idempotency key. The PSP debits your float account and initiates the PIX credit to the player. Settlement to the player's bank account is instant on the SPI rail, but your PSP may impose batch windows or float requirements that add latency. This is a contract negotiation point, not a technical limitation.
One architectural decision that trips up operators coming from European markets: PIX does not have a native refund flow the way card schemes do. If you need to reverse a deposit (fraud reversal, duplicate charge, etc.), you initiate a new outbound PIX transfer back to the player's key. Your platform needs to handle this as a distinct payout workflow, not a refund call. Build that into your integration spec from day one, or you will be patching it post-launch under pressure.
Which PSPs and Payment Providers Actually Support PIX for iGaming Operators?
The Brazilian PIX PSP market splits into three tiers for casino operators: iGaming-native Brazilian processors (Pay4Fun, Vaga Wallet, Barte), global aggregators with local PIX rails (Nuvei, Paysafe, Worldline Brazil), and direct Brazilian Payment Institution relationships (Zoop, Celcoin, Iniciador Pagamentos). Each tier has a different risk appetite, onboarding timeline, and fee structure.
Pay4Fun and Vaga Wallet are the names I see most consistently in iGaming-specific PIX integrations. Both are registered Payment Institutions with Banco Central and have built their products specifically around the casino deposit/withdrawal use case, they understand float management, high-frequency small-ticket transactions, and the withdrawal SLA expectations Brazilian players have. Pay4Fun in particular has been in this space since before PIX existed, originally processing Boleto, and they migrated their infrastructure to PIX rails early. Their API documentation is solid and their integration support is responsive, which matters when you are debugging a webhook mismatch at 2am before a soft launch.
Nuvei entered Brazil aggressively in 2022 and 2023 and now has a credible PIX offering for operators who want a single global contract covering multiple markets. The trade-off is that their Brazilian entity operates as a sub-participant through a local IP partner, which can add a processing hop and occasionally shows up as slightly higher latency on withdrawals compared to a direct IP relationship. For operators already using Nuvei for EU or LATAM markets, the consolidation benefit often outweighs that latency delta. Paysafe's Skrill and Neteller products have Brazilian PIX support but are better suited for players who already have those wallets, the conversion funnel for new Brazilian players opening a Skrill account just to deposit at your casino is not great.
Direct relationships with Brazilian IPs like Zoop or Celcoin are worth considering if you are processing at scale (think north of BRL 10 million monthly) and want to own more of the margin. These are bank-grade onboarding processes, expect 8 to 14 weeks, a Brazilian CNPJ entity requirement, full KYB documentation, and a compliance interview. The MDR (merchant discount rate) can drop to 0.3 to 0.6 percent at volume versus 1.5 to 2.5 percent through an iGaming-focused aggregator. That spread is meaningful at scale, but the operational overhead is real.
| Provider Tier | Examples | iGaming Focus | Onboarding Time | Typical MDR | CNPJ Required |
|---|---|---|---|---|---|
| iGaming-Native Brazilian IP | Pay4Fun, Vaga Wallet, Barte | High | 3-6 weeks | 1.2-2.5% | Usually yes |
| Global Aggregator (local rail) | Nuvei, Worldline Brazil | Medium | 4-8 weeks | 1.5-2.8% | Varies by structure |
| Direct Brazilian IP | Zoop, Celcoin, Iniciador | Low (general) | 8-14 weeks | 0.3-0.8% at volume | Yes, mandatory |
| E-wallet with PIX backend | Paysafe/Skrill, PicPay | Low | 2-4 weeks | 2.0-3.5% | No, but limited reach |
What Are the Compliance Requirements for PIX in a Licensed Brazilian Casino?
Under Lei 14.790/2023 and SECAP/MF Portaria 1.330/2023 and subsequent normative acts, licensed operators must process all financial transactions through regulated Brazilian payment institutions, implement CPF-matched deposit and withdrawal flows, and maintain transaction records for at least five years. Using an unlicensed offshore aggregator to route Brazilian PIX transactions is a compliance violation that can cost you your license.
The CPF matching requirement deserves specific attention because it is the rule operators most commonly mishandle. The regulation requires that the CPF used to register the player account matches the CPF of the PIX key used for deposits and withdrawals. This means you cannot allow a player to deposit from their spouse's account or a business CNPJ key. Your platform needs to validate the payer CPF at the webhook level, when the PIX credit arrives, extract the payer's CPF from the transaction metadata the PSP returns, compare it to the CPF on file for that player account, and reject or flag mismatches. Most iGaming-native PSPs have a flag for this in their webhook payload. If yours does not, ask for it explicitly before signing the contract.
AML obligations under Brazil's Lei 9.613/1998 (as updated) and COAF reporting requirements apply to licensed casino operators. PIX's identity infrastructure helps, but you still need a transaction monitoring system that flags structuring patterns, rapid deposit-withdrawal cycles, and high-value single transactions above the COAF reporting threshold (currently BRL 50,000 for financial institutions, though the threshold applicable to betting operators specifically should be confirmed with your compliance counsel as the regulatory guidance was still being finalized through 2024 and 2025). Do not assume your PSP handles this for you, they handle their own COAF obligations, not yours.
One practical trap: some operators incorporate a foreign entity (often a Curaçao-licensed holding company) and try to receive Brazilian PIX settlements into a foreign bank account via a payment intermediary. This structure will not survive regulatory scrutiny under the 2023/2024 Brazilian iGaming framework. You need a Brazilian legal entity receiving BRL settlements, and that entity needs to be the contracted party with your PSP. Get this right in your corporate structure before you start PSP onboarding, not after, unwinding it is expensive and slow.
How Long Does PIX Casino Integration Actually Take, and What Drives the Timeline?
A realistic PIX integration for a casino operator takes 4 to 10 weeks from signed PSP contract to production go-live. The main variables are your platform's API readiness, the PSP's KYB process, whether you need a new Brazilian CNPJ entity, and how quickly your development team can build and QA the deposit, withdrawal, and CPF-matching flows.
Week one and two are almost always consumed by PSP onboarding documentation. Expect to provide: certificate of incorporation for your operating entity, beneficial ownership structure down to the UBO level, proof of gambling license (or pending license application), bank statements, a business plan describing your Brazilian operation, and in some cases a technical questionnaire about your platform's fraud and AML controls. iGaming-native PSPs like Pay4Fun have seen these packs before and move faster. General-purpose Brazilian IPs will treat you like a new corporate banking client and move at banking speed.
Technical integration, assuming your platform has a reasonably modern REST API architecture, takes 1 to 3 weeks for a competent backend developer. The core endpoints are: create charge (deposit QR), webhook receiver (deposit confirmation), initiate payout (withdrawal), and payout status check. The CPF validation logic, idempotency handling, and reconciliation reporting add time. If you are on a white-label platform like SoftSwiss or EveryMatrix, check whether PIX is already in their payment module, both platforms had Brazilian PIX integrations available by 2024, which can cut your technical timeline to days rather than weeks, though you still go through PSP KYB.
QA and staging environment testing is where timelines slip most often. PIX sandbox environments vary in quality, some PSPs have robust test environments that simulate the full webhook flow, others have sandboxes that do not accurately reflect production latency or error codes. Budget time for production testing with small real transactions before you open to players. The edge cases that matter most: what happens when the player's bank is down and the PIX times out, what happens when a duplicate webhook fires, and what happens when the payout fails because the player's PIX key is no longer active. All three will happen in production within your first week of operation.
What Does PIX Integration Cost, and How Do You Structure the Fee Negotiation?
PIX processing costs for iGaming operators typically run 1.0 to 2.5 percent MDR on deposits, with payouts often priced separately at BRL 1.50 to BRL 4.00 per transaction or a flat percentage. Setup fees range from zero (iGaming-native PSPs competing for your business) to BRL 20,000 or more for direct IP relationships. Volume commitments unlock better rates.
The MDR is the headline number, but it is not the only cost. Watch for: monthly minimum fees (common with smaller PSPs who want revenue certainty), chargeback or dispute fees (less relevant for PIX than cards, but some PSPs charge an admin fee for any transaction dispute), float or reserve requirements (some PSPs hold 5 to 10 percent of your monthly volume in reserve for 30 to 90 days, that is working capital you need to plan for), and FX fees if your PSP settles in USD or EUR rather than BRL.
Fee negotiation works best when you come with volume projections and a competitive offer in hand. If you are talking to Pay4Fun and Nuvei simultaneously, both know the market and will move on price if you give them a realistic monthly volume target. A platform processing BRL 5 million per month is a different conversation than one processing BRL 500,000. Be honest about your projections, PSPs that specialize in iGaming have seen enough operator decks to spot inflated numbers, and starting a relationship with unrealistic projections damages trust before you even go live.
One cost operators frequently overlook: the float account. Your PSP will require you to maintain a funded float (or pre-fund) to cover outgoing PIX payouts. The size depends on your withdrawal volume and the PSP's settlement cycle. If your PSP settles your deposit receipts to you daily, you can recycle that float efficiently. If they settle weekly, you may need to maintain a float equal to several days of withdrawal volume. At scale, that is a meaningful cash management decision. Model it out before you sign.
| Monthly Volume (BRL) | Typical Deposit MDR | Payout Fee | Reserve Requirement | Setup Fee Range |
|---|---|---|---|---|
| Under 500K | 1.8-2.5% | BRL 2.50-4.00 per txn | 10% / 60 days | BRL 0-5,000 |
| 500K - 5M | 1.2-1.8% | BRL 1.50-2.50 per txn | 7-10% / 30-60 days | BRL 0-10,000 |
| 5M - 20M | 0.8-1.3% | BRL 1.00-1.80 per txn | 5-7% / 30 days | BRL 5,000-15,000 |
| Above 20M | 0.3-0.8% | BRL 0.50-1.20 per txn | 3-5% / 30 days | Negotiated |
How Do You Optimize PIX for Conversion and Withdrawal Speed?
Conversion optimization for PIX centers on three things: minimizing the steps between the player clicking 'deposit' and the QR code appearing on screen, matching the deposit amount exactly to what the player typed (no rounding), and crediting the player wallet within 5 seconds of the PSP webhook firing. Withdrawal speed is the retention lever, sub-10-minute payouts measurably reduce churn.
The deposit UX flow matters more than most operators realize. Brazilian players are extremely comfortable with PIX, they use it for groceries, rent, and everything else. What they are not comfortable with is a clunky casino deposit flow that makes them re-enter their CPF, navigate three confirmation screens, and wait 45 seconds for a QR code to load. The QR code should appear in under 2 seconds. The Copia e Cola string should be one tap to copy. The expiry timer (PIX QR codes expire, typically in 30 minutes, though your PSP may configure shorter windows) should be visible. If the code expires before the player pays, your platform needs to auto-generate a new one without making the player restart from scratch.
On the withdrawal side, the operational variable is your PSP's payout processing window. Some PSPs process outgoing PIX payouts in real time 24/7 (PIX operates 24 hours a day, 365 days a year, including holidays, this is one of its genuine advantages over TED/DOC). Others batch payouts hourly or have manual review queues for amounts above a threshold. Know your PSP's actual payout SLA before you promise players anything in your terms. A player who requests a withdrawal at 11pm on a Sunday and gets it in 8 minutes will tell people. A player who waits 4 hours will complain publicly.
Responsible gambling and AML controls can add friction to withdrawals if they are implemented clumsily. A withdrawal that triggers a KYC document request every time, or that routes through a manual review queue for amounts as low as BRL 200, will destroy your NPS. Design your risk thresholds thoughtfully: automate the low-risk majority, reserve manual review for the genuinely anomalous cases. Your compliance team and your product team need to agree on those thresholds before launch, not after your first player complaint thread appears on a Brazilian forum.
What Are the Biggest PIX Integration Mistakes Operators Make?
The most expensive PIX integration mistakes I have seen are: skipping CPF validation on deposits (creates compliance exposure and bonus abuse vectors), using a PSP not licensed by Banco Central do Brasil (creates regulatory risk under the new Brazilian iGaming framework), and failing to build a proper reconciliation layer (creates financial discrepancies that compound daily and are painful to unwind).
CPF validation failures are surprisingly common. An operator builds the basic deposit and withdrawal flow, tests it with their own accounts, everything works, they go live. Three weeks later, a bonus abuse ring has figured out that they can deposit from multiple CPFs into a single account because the platform is not validating the payer CPF against the registered CPF. The PSP returns the payer CPF in every webhook, you just have to check it. Build the check, log mismatches, and decide your policy (reject, flag for review, or allow with a note) before you go live.
PSP due diligence failures are the other big one. I have spoken to operators who integrated a Brazilian payment intermediary that turned out to be operating without a Banco Central registration, relying on a sub-participant arrangement that was not properly disclosed. When Brazilian regulators started scrutinizing iGaming payment flows in 2024, those operators had to scramble to replace their payment stack mid-operation. Always verify your PSP's Banco Central registration directly on the BCB's public registry (registrato.bcb.gov.br) before signing. This takes 10 minutes and could save your license.
Reconciliation is the unglamorous one. PIX transactions arrive fast and in high volume. If your platform's transaction log and your PSP's settlement report do not match to the cent, you have a problem that gets worse every day you do not fix it. Build automated reconciliation from day one: daily comparison of your platform's credited deposits against the PSP's settlement report, flagging any discrepancy above a defined threshold for manual review. Most iGaming platforms (SoftSwiss, EveryMatrix, Softgamings) have reconciliation modules, but they need to be configured correctly for PIX's settlement timing. Do not assume it works out of the box.
How Does the Brazilian iGaming License Affect Your PIX Payment Setup?
Brazil's licensed iGaming framework under SECAP/MF requires operators to hold a federal betting license (Licença de Operação) to legally offer online casino games. The license application process, which opened in 2024, requires operators to demonstrate compliant payment infrastructure as part of the technical requirements. Your PSP must be a regulated Brazilian Payment Institution, and your financial flows must be transparent and auditable.
The Brazilian federal license process is managed by the Secretaria de Prêmios e Apostas (SPA/MF), which was created specifically to regulate sports betting and online gaming following Lei 14.790/2023. License fees and requirements were still being finalized through 2024 and into 2025, so operators should verify current requirements directly with SPA/MF or through Brazilian gaming law counsel rather than relying on any single secondary source (including this article). What is clear is that payment compliance is not optional or reviewable post-license, it is part of the application.
For operators currently operating under a Curaçao or Malta license and serving Brazilian players in a grey-market capacity, the transition to a Brazilian federal license involves restructuring your payment stack. The offshore PSP arrangement that worked in the grey market will not satisfy SPA/MF requirements. You need a Brazilian CNPJ entity, a Brazilian bank account, a Banco Central-registered PSP, and CPF-matched transaction flows. Budget 3 to 6 months for this restructuring, not 3 to 6 weeks. The corporate and banking setup alone takes time even when everything goes smoothly.
Tax implications are part of this picture too. Licensed Brazilian operators are subject to Brazilian corporate income tax (IRPJ/CSLL) and potentially ISS (municipal services tax) on their GGR. PIX settlements are in BRL, so there is no FX complexity on the domestic side, but operators with foreign parent entities need transfer pricing and dividend repatriation structures that comply with both Brazilian and home-country tax rules. This is a conversation to have with a Brazilian tax attorney before you structure your entity, not after your first profitable quarter.
How Does PIX Compare to Other Brazilian Payment Methods for Casino Operators?
PIX dominates Brazilian casino payments by every relevant metric: settlement speed (instant vs. 1-3 days for Boleto), conversion rate (higher, because players do not need a credit card), chargeback rate (near zero vs. 1-3 percent for cards), and market penetration (over 150 million registered PIX keys as of 2024). The only scenario where another method outperforms PIX is high-ticket VIP deposits where credit card rewards points matter to the player.
Boleto bancário was the default Brazilian online payment method before PIX existed, and some operators still support it for players who lack a bank account with PIX enabled (a shrinking demographic). The fundamental problem with Boleto for casino operators is the 1 to 3 business day settlement window. A player who generates a Boleto, pays it, and then has to wait until the next business day to see their casino balance credited is a player who has had 24 hours to reconsider. Boleto abandonment rates are high in iGaming specifically because of this friction. I would not build a primary payment strategy around Boleto in 2026, support it as a fallback for the unbanked segment if your compliance team approves it, but do not optimize for it.
Credit and debit cards (Visa, Mastercard) face a different problem: issuer-level blocking of gambling MCCs. Brazilian card issuers have historically blocked or declined a significant share of gambling-coded transactions, and while the licensed framework may improve this over time, operators should expect decline rates of 20 to 40 percent on card transactions compared to near-zero decline rates on PIX. Cards also carry chargeback exposure that PIX does not. That said, some high-value players prefer cards for the rewards points and credit float, so supporting Visa/Mastercard as a secondary option makes sense if your PSP offers it without significant incremental cost.
| Method | Settlement Speed | Typical Decline Rate | Chargeback Risk | Market Penetration | Operator Recommendation |
|---|---|---|---|---|---|
| PIX | Instant (under 10 sec) | Under 2% | Near zero | Very high (150M+ keys) | Primary method, mandatory |
| Boleto Bancário | 1-3 business days | Low (abandonment high) | None | Medium (declining) | Fallback only |
| Credit/Debit Card | Instant auth, T+1 settle | 20-40% (gambling MCC) | 1-3% of volume | High (but blocked) | Secondary, VIP focus |
| Digital Wallets (PicPay, etc.) | Near-instant | Low | Low | Medium | Optional, niche use |
| Crypto (BTC, USDT) | 10 min - 1 hour | Near zero | None | Low (growing) | Optional, tech-savvy segment |
Comments
No comments yet, be the first.